IEEPA Tariff Refunds: What Importers Should Check
IEEPA tariff refunds go to the importer of record. What to check in ACE, what to ask vendors who charged you a tariff surcharge, and a worked example.
Contents
IEEPA tariff refunds are being paid, and who receives them depends on who was the importer of record on each entry. If it was you, you have a claim to file and a landed cost to re-baseline. If it was your distributor or a DDP supplier, the refund goes to them, and the surcharge you paid stays with them unless you ask.
Below: three checks, a worked example and a dated action list. Last checked: 8 October 2026. This is commercial guidance, not legal, customs or tax advice.
In Short
- The Supreme Court decided Learning Resources, Inc. v. Trump on 20 February 2026. The Court's summary: IEEPA does not authorize the President to impose tariffs.
- An executive order signed the same day ended the IEEPA duties and directed agencies to stop collecting them as soon as practicable.
- CBP refunds IEEPA duties, with interest, through CAPE in ACE, generally 60 to 90 days after accepting a declaration, and only to the importer of record or a party it names on CBP Form 4811.
- If your vendor imported, ask in writing what happens to the surcharge you paid. The refund will not reach you any other way.
Check 1: Were You the Importer of Record?
CBP's current scope: Phase 1 covers certain unliquidated entries and entries within 80 days of liquidation; Phase 2 covers entries flagged for reconciliation where the reconciliation entry is not yet on file. CBP lists other types, including finally liquidated entries, entries under an open protest and certain AD/CVD entries, as being evaluated for later deployments. For Phase 1 entries CBP says no Court of International Trade case is needed; for others it gives no legal guidance.
To claim you need an ACE Portal account with the Importer sub-account, refund bank details enrolled for ACH, and a CAPE Declaration filed by you or your broker. Then re-baseline any landed cost or customer price built on IEEPA rates. The landed cost formula shows where duty sits in the sum.
Check 2: Did a Vendor Import and Charge You a Surcharge?
CBP states that it can only refund the importer of record or the Form 4811 notify party; buyers further down the chain receive nothing from CBP. So if a distributor or DDP supplier charged you an IEEPA-era surcharge, it recovered the duty cost from you through that surcharge and is now being refunded the same duty, with interest, by CBP.
What you can ask for depends on your terms and the wording of the surcharge, which can be a legal question. Start with the surcharge notices, the invoices that carried them and the period each covered.
Check 3: Was the Surcharge Relabelled?
IEEPA duties ended in February. A 10% Section 122 surcharge applied from 24 February 2026 for 150 days, and forced labour Section 301 duties have applied since 24 July 2026. A surcharge that ran on through those changes may now rest on a different tariff, rate and date. Test each period separately, with the method in tariff surcharges on supplier invoices.
Worked Example: Setting the Floor and the Ceiling
The 10% rate is an example, not a statement of any product's rate.
A US retailer buys a line from a US distributor at USD 25.00 a unit. The distributor imports it and, in 2025, added an 8% tariff surcharge citing IEEPA tariffs: USD 2.00 a unit. The retailer bought 30,000 units while the surcharge applied.
- Surcharge paid: 30,000 x 2.00 = USD 60,000.
- The distributor's entered value is USD 11.00 a unit, and the IEEPA rate on the line was 10%: duty of USD 1.10 a unit, or 30,000 x 1.10 = USD 33,000 on the retailer's units.
- The distributor files a CAPE Declaration and is refunded the USD 33,000 on those units, plus interest.
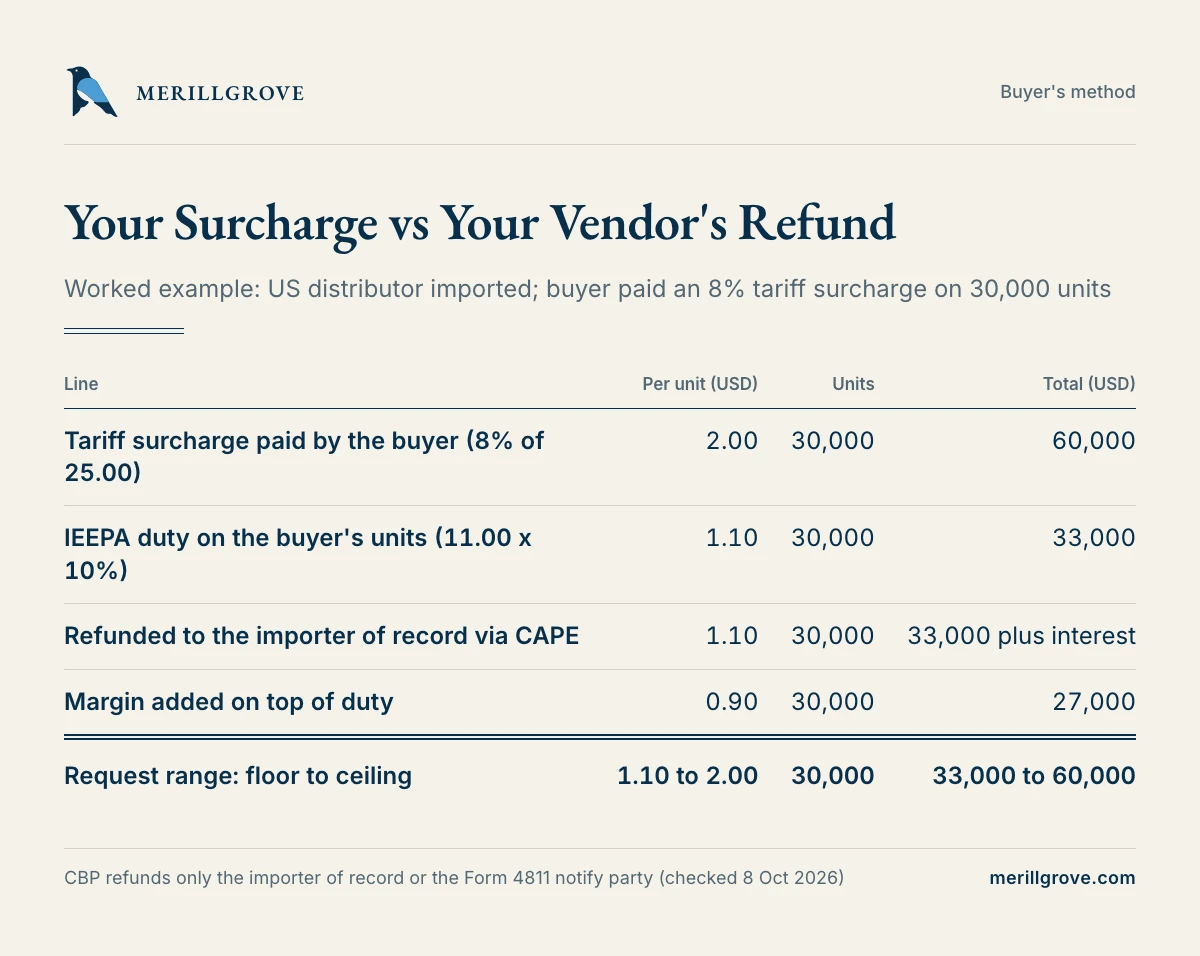 *Floor and ceiling for a refund request to a vendor.*
The retailer's request has a floor of USD 33,000, the duty on its units that the distributor is getting back, and a ceiling of USD 60,000, what it paid. The USD 27,000 between them is margin added on top of duty. The retailer asks for the full surcharge, offers to settle at the refunded duty as a credit against future orders, and asks for confirmation that the surcharge stopped when the IEEPA duty did.
Action List, Dated
- By 16 October: if you import, pull your entries with IEEPA Chapter 99 lines from ACE. Check that ACH refund enrolment is in place.
- By 23 October: file CAPE Declarations for eligible entries, or confirm your broker has.
- By 23 October: list every vendor surcharge since early 2025 that cited tariffs. For each, record the importer of record, the tariff named, the rate and the dates.
- By 31 October: write to each vendor that imported. Ask when it stopped paying IEEPA duty, when the surcharge stopped, and how it will treat the refund on your units.
- Late December 2026 to January 2027: declarations accepted in late October should, on CBP's 60 to 90 day guide, pay out. Reconcile what arrives.
- Ongoing: watch CBP's CAPE page for the next deployment if any entries sit outside Phases 1 and 2.
If a vendor answers with a new price instead, treat it as a price increase and test it: see how to respond to a supplier price increase. If China-origin lines are also affected by the exclusion end date, see Section 301 exclusions ending in November.
Tools for the Reply
Start with the free 12 checks and justified-increase quick calculator: get the checklist.
Sources (checked 8 October 2026): Supreme Court of the United States, Opinions of the Court (Learning Resources, Inc. v. Trump, 24-1287), https://www.supremecourt.gov/opinions/slipopinion/25; Federal Register, Ending Certain Tariff Actions (2026-03832), https://www.federalregister.gov/documents/2026/02/25/2026-03832/ending-certain-tariff-actions; Federal Register, Imposing a Temporary Import Surcharge (2026-03824), https://www.federalregister.gov/documents/2026/02/25/2026-03824/imposing-a-temporary-import-surcharge-to-address-fundamental-international-payments-problems; Federal Register, Notice of Actions in Section 301 Investigations (2026-15181), https://www.federalregister.gov/documents/2026/07/28/2026-15181/notice-of-actions-in-section-301-investigations-of-acts-policies-and-practices-of-various-economies; CBP, IEEPA Duty Refunds, https://www.cbp.gov/trade/programs-administration/trade-remedies/ieepa-duty-refunds. Last checked: 8 October 2026. Commercial guidance, not legal, customs or tax advice.
Want This Checked for You?
Send the notice, the quotes or the supplier details. We tell you what to question first, and the fee is agreed before any work starts.
More on Trade Triggers
 Trade TriggersUS Wood Products Tariff Rises on 1 January 2027: Cabinets, Vanities and FurnitureSection 232 duty on kitchen cabinets and vanities rises from 25% to 50%, and on upholstered wooden furniture to 30%, on 1 January 2027. A dated plan.
 Trade TriggersEU Steel Safeguard Changes in 2026: What Steel Buyers Should CheckThe EU's new steel regime: quotas from 1 July 2026, a 50% out-of-quota duty and melt and pour evidence from 1 October. How to test a steel surcharge.
 Trade TriggersAnti-Dumping Duties in Australia: Check Your Supplier ListAustralian dumping duty is set by goods, country and exporter. A six-step exposure check for your supplier list, a landed cost example and dates to watch.